Article 2 of 3 in the special series on cryptocurrencies and the future of business
In the first article of this series, we saw that cryptocurrencies have moved beyond speculation and started becoming infrastructure, with banks, ETFs and regulation driving the transformation.
Today we move from the big picture to the shop floor.
The topic is the one that matters most to anyone running a business: payments.
More specifically, stablecoins, the digital currencies pegged to traditional money such as the dollar, and the quiet way they are changing how money is sent and received across borders.
The number that captures the moment comes from an Allium report on stablecoins and payments, published in September 2026: stablecoin payments grew 42% and totaled at least $401 billion in the first eight months of the year, while total stablecoin supply grew only 6%.
In other words: money held in stablecoins is not sitting idle in wallets. It is circulating.
And most of that circulation does not come from investors. It comes from businesses.
What a stablecoin is, in one sentence
A stablecoin is a digital token designed to always be worth the same as a traditional currency, usually the dollar.
If you hold 100 USDC, you hold the digital equivalent of 100 dollars, backed by reserves the issuer must maintain and disclose.
This solves the biggest obstacle to using cryptocurrencies for payments: volatility.
No business wants to receive a payment that could be worth 20% less the next day. With stablecoins, the value received remains stable, while the transfer happens on blockchain rails, with the speed and cost of the internet rather than of the international banking system.
The numbers show who is using them
The Allium report includes details that reveal the nature of this adoption.
Businesses receive between 58% and 64% of all stablecoin payments. These are not consumers buying out of curiosity. They are companies settling invoices, paying suppliers and managing treasury.
Cross-border stablecoin payments are growing seven times faster than conventional fiat rails.
In the B2B segment, the growth is even more explicit: according to industry data compilations, business-to-business stablecoin payments grew 733% in 2025, reaching about $226 billion in volume.
And the EY-Parthenon survey of corporations points to the dominant use case: cross-border supplier settlement, cited by 77% of companies already using the technology.
Why businesses are migrating: a problem nobody solved for decades
To understand the appeal, you need to understand what the traditional system does to an international payment.
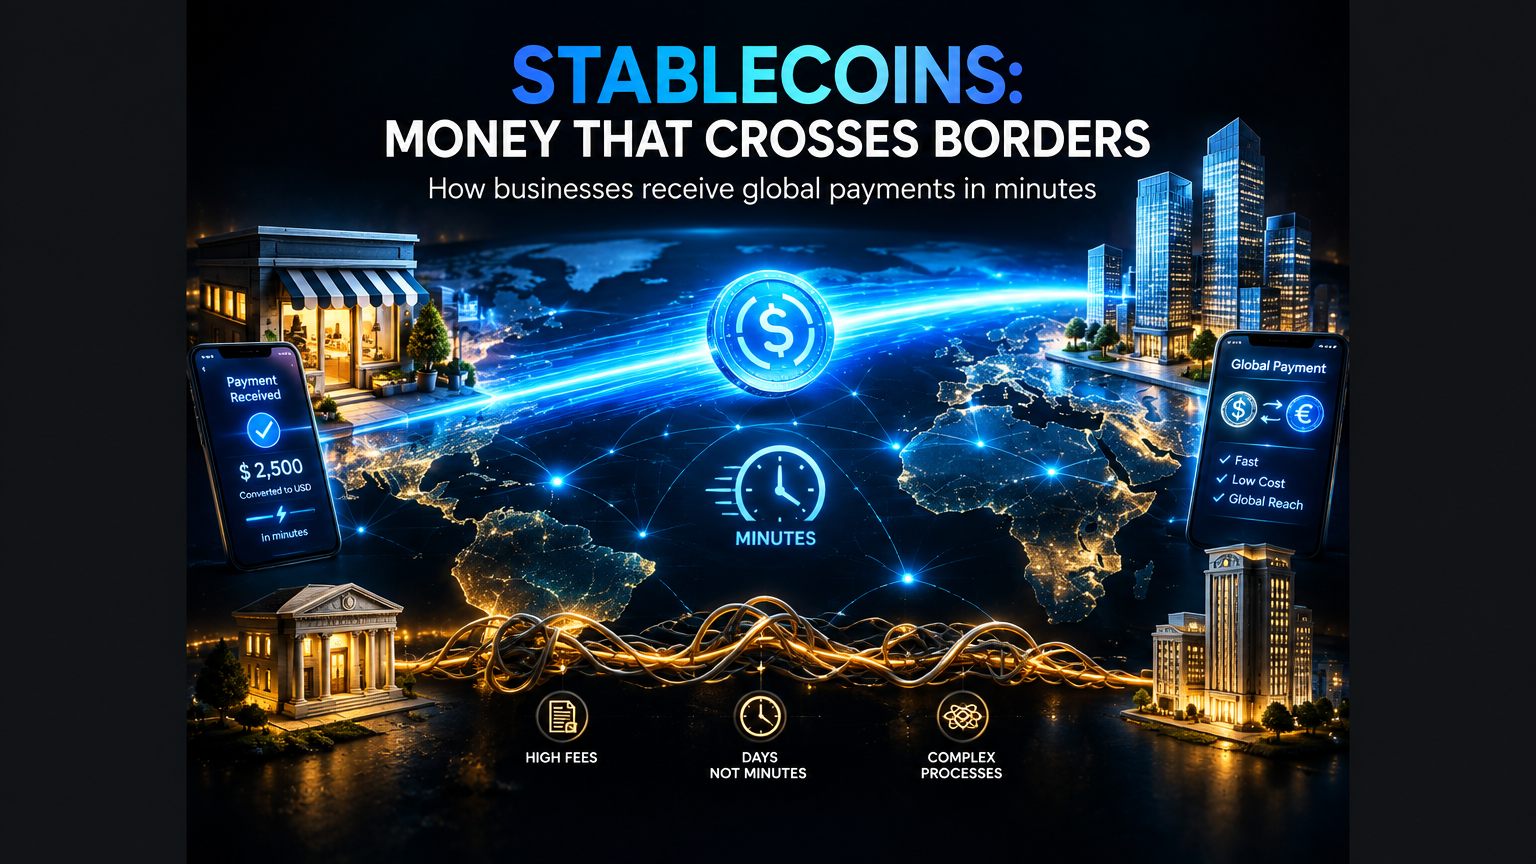
Imagine a Brazilian company selling services to a client in Europe. The client pays in euros, the money crosses correspondent banks, each one charges its fee, each stage consumes days. The total cost of that journey typically runs between 3% and 7% of the value, and settlement takes 2 to 5 business days.
For small remittances, the picture is worse. Industry data points to costs near 6.5% on 200-dollar transfers, with specific corridors between developing countries exceeding 12%.
Now compare it with the stablecoin path, known as the sandwich model:
- The client converts local currency into a stablecoin.
- The stablecoin crosses the blockchain in minutes, with a network fee that is usually under one dollar.
- The receiver converts the stablecoin into local currency.
The total cost of that journey typically falls between 0.5% and 2.5%, and settlement takes minutes, not days.
For a company earning in foreign currency, that difference is not a technical curiosity. It is margin. Cash flow changes too: receiving in minutes instead of waiting a week changes how the business turns over capital.
The Citi and Coinbase case: when the bank builds the bridge
The news that marked the end of September 2026 shows how fast the traditional system is absorbing this.
Citi, one of the largest U.S. banks, expanded its collaboration with Coinbase on two fronts, according to the companies’ official announcement.
On the first front, Coinbase chose Citi’s Virtual Account Wallet to power its virtual accounts, creating fiat wallets that automatically convert incoming funds into stablecoins.
On the second, Citi’s institutional clients will be able to accept stablecoin payments at checkout through the Spring by Citi platform, with Coinbase providing the digital infrastructure and automatic conversion into traditional currency. Citi settles as the bank of record.
The most important detail of this partnership is what it eliminates.
The bank’s merchant client does not need to hold cryptocurrencies, does not need to understand blockchain and does not need to build its own infrastructure. It accepts a digital payment and receives dollars in its account, like any banking operation.
The Wall Street Journal highlighted that Coinbase will provide the digital rails for Citi’s corporate clients. It is a complete reversal of the historical narrative: instead of crypto against banks, crypto inside banks.
This pattern is repeating elsewhere. Coinbase partnered with MassPay for corporate cross-border payouts and, together with Moov, is bringing stablecoin acceptance to community banks and credit unions in the United States.
The regulation holding it all together
No serious company would adopt stablecoin payments in a murky regulatory environment.
That is why the approval of the GENIUS Act in the United States, in July 2025, worked as a trigger. The law created the first federal framework for payment stablecoins, requiring:
- full backing with liquid assets;
- monthly public disclosure of reserve composition;
- compliance with anti-money-laundering legislation.
On September 24, 2026, the Federal Reserve moved forward with proposed rules to implement the law, including standards for stablecoin yield programs. In Europe, the MiCA regulation is already in force and completed its transition period in 2026.
The practical result is that, for the first time, a company can adopt stablecoins knowing which issuers are regulated, which reserves are audited and which rules apply to each operation.
Regulatory clarity turned the stablecoin from a regulatory risk into a treasury tool.
Real use cases for businesses
Adoption is not theoretical. These are the scenarios where stablecoins already operate:
Receiving from international clients
Service providers, agencies, developers and consultants who invoice abroad receive in stablecoin and convert to local currency, cutting intermediary fees.
Paying foreign suppliers
The dominant case according to the EY-Parthenon survey. Paying a supplier in Asia or Europe in minutes, with predictable cost, instead of waiting days for bank processing.
Dollar treasury
Companies in countries with volatile currencies keep part of their cash in regulated stablecoins, with immediate liquidity and without depending on bureaucratic foreign accounts.
Cross-border e-commerce
Stores selling to regions with limited banking access accept stablecoin and reach customers that traditional cards cannot reach.
Mass payouts
Companies with many payers or payees, such as gig platforms and marketplaces, execute hundreds of simultaneous transfers at near-zero cost.
Among corporations already using stablecoins, 41% report cost savings as the main perceived benefit, according to industry compilations.
What to consider before adopting
Enthusiasm does not eliminate the need for criteria. Before incorporating stablecoins into an operation, a business should evaluate:
The issuer
Prefer regulated stablecoins with audited reserves and public disclosure. The GENIUS Act and MiCA created precisely that selection layer.
Conversion into local currency
The sandwich model depends on a reliable conversion bridge. Established platforms and banking partnerships, such as Citi with Coinbase, reduce that risk.
Taxation and accounting
Each conversion may generate an accounting and tax event. The company needs to define with its accountant how to record inflows, conversions and outflows.
Operational security
Wallets require key management and procedures. For businesses, the safer path is using platforms with regulated custody instead of self-management.
The real use case
Stablecoins are not a universal solution. If the company has no international flow, the gain is marginal. If it does, the gain is direct and measurable.
Where your business technology fits into this story
Adopting stablecoin payments is not just opening an account. It is integrating a new channel into processes that already exist: invoicing, reconciliation, CRM, notifications, reporting.
This is where the conversation returns to the ground of this blog.
A company receiving in stablecoin needs its system to recognize the payment, update the order, issue the receipt and notify the client, all automatically. It needs incoming data to land in the same base as card and transfer data, so the financial view stays unified.
This is exactly the kind of integration Rapid Genius builds with intelligent automation: connecting tools, eliminating manual work and ensuring every payment, in any format, flows through the process without human intervention at each step.
The same applies to the digital storefront. A website that accepts multiple payment methods, including new digital channels, needs to be well structured, fast and secure. That is the work Rapid Genius delivers in website and app development, focused on conversion and experience.
And as transaction volume grows, data analysis becomes decisive for understanding margin by channel, cost per payment method and international customer behavior. That is the field of data science applied to business.
Payment technology changes. The principle remains: those who organize their processes capture the benefit; those who improvise accumulate problems.
The honest limits of this trend
A balanced article needs to mark what is still unresolved.
Local conversion infrastructure remains uneven across countries. In some markets, converting stablecoin into local currency at a good rate is still the bottleneck.
Accounting and tax treatment vary by jurisdiction and are still being consolidated.
Corporate adoption concentrates in companies with international flows. For purely local businesses, the practical benefit today is limited.
And the market itself is still under construction: the Federal Reserve is still in the proposal stage, which means operational details may change.
None of this invalidates the trend. But it separates strategic adoption from fad adoption.
What is coming in article 3
We closed the landscape in article 1 and the payment applications here.
In the final article of the series, we go to the foundation: blockchain beyond money. Smart contracts, asset tokenization, supply chain traceability and the use cases that already work for businesses, separated from those that are still sales-pitch promises.
Conclusion: international payments have run out of excuses
For decades, sending and receiving money across borders was expensive, slow and opaque because no structural alternative existed.
One now exists, is regulated in the main markets and is being integrated by the world’s largest banks.
The numbers tell the story: $401 billion in payments over eight months, businesses receiving the majority, growth seven times higher than traditional rails, and a century-old bank building the official bridge.
The question for your business is no longer:
“Does this work?”
It is:
“What does each international payment my company sends or receives cost today, and what would it cost on digital rails?”
Running that calculation is the first step.
In the next article, we close the series by looking at the engine underneath it all.
See you there.